You've decided it's time to speak with a counsellor in Kelowna. You've found someone who seems like a good fit, but one question keeps getting in the way: will your extended health plan pay for therapy? The answer often depends less on whether your plan includes “mental health” and more on the provider's designation, your remaining annual maximum, the billing process, and the rules for dependents. For more information, see our Kelowna couples counselling.
Checking those details before your first appointment can prevent a declined claim or an unexpected interruption in care. This guide walks through the practical process, from understanding MSP and workplace benefits to confirming eligibility, choosing direct billing or receipt reimbursement, submitting claims, and planning when coverage is limited. For more information, see our counselling in Kelowna.
Why Extended Health Benefits Matter for Counselling in Kelowna
A Kelowna resident might start the week feeling overwhelmed by anxiety, grief, relationship strain, or burnout. They may know counselling could help, yet hesitate because private therapy isn't covered through the provincial plan. In British Columbia, psychotherapy or counselling from a private practitioner isn't covered by MSP, so people generally rely on extended health insurance or pay privately, as explained by Here to Help's guidance on paying for mental health care. For more information, see our couples counselling.
That gap makes workplace or personal benefits an important practical resource. Extended health counselling coverage can help someone access support sooner, rather than waiting until distress affects sleep, work, parenting, or relationships. It doesn't guarantee unlimited care, though. A plan may recognise counselling while limiting the eligible provider, reimbursement amount, annual maximum, or number of sessions.
Why earlier support can matter
British Columbia has a higher unmet or partially met need for mental health and addictions care than Canada overall, 9.4% compared with 7.8% nationally, according to the Canadian Mental Health Association's 2024 State of Mental Health report. The same report records a 30-day hospital readmission rate of 15.3% in BC, compared with 13.4% nationally, for mental health and substance-use concerns.
Those figures don't predict what will happen to any individual. They do show why accessible outpatient counselling and follow-up support matter. For someone in Kelowna, benefits may make it easier to use in-person, phone, or secure virtual sessions within a plan, depending on the insurer's rules and the clinician's eligibility.
Treat benefits as a tool, not a test
Many first-time clients feel embarrassed about asking a therapist or insurer basic questions. You don't need to understand insurance language before you begin. A benefits check is a way to learn what your plan will support.
Your path may involve an employer portal, a call to the insurer, direct billing, or submitting receipts yourself. Each step is manageable, and asking early is a form of self-advocacy. The aim isn't to make therapy feel administrative. It's to protect your access to care once you've decided support would help.
How to Check Your Extended Health Coverage Before You Book
Your benefits booklet may use several labels for therapy, including counselling, psychological services, mental-health practitioners, or paramedical services. Start with the insurer's website or mobile app, then check the full plan booklet if the summary is unclear. Human resources can usually identify the insurer and plan administrator, but the insurer is the party that can confirm claim-specific eligibility.
Ask about the provider designation
Don't assume every therapist is reimbursed under the same category. Ask whether the plan covers:
- Registered Clinical Counsellors, often listed as RCCs
- Psychologists
- Registered Social Workers, sometimes listed as RSWs
- Regulated psychotherapists or other approved practitioners, where applicable
BC plans are inconsistent about eligible designations. Recent plan changes show broader recognition of providers such as registered clinical counsellors, social workers, marriage and family therapists, and online cognitive behavioural therapy, but plan-specific limits still apply. The BC government counselling support information also illustrates why approval status and dependent rules need to be checked rather than assumed.
Confirm the financial rules
Write down the answers to these questions:
- Annual maximum: What is the yearly reimbursement limit for counselling or mental-health services?
- Per-session limit: Does the plan reimburse the full eligible amount, or only up to a set amount per visit?
- Remaining balance: How much of the current maximum is still available?
- Deductible or co-insurance: Does the plan require you to pay part of each eligible claim?
- Reasonable-and-customary limit: Will the insurer cap reimbursement below the therapist's actual fee?
- Referral requirement: Does a physician's referral or assessment form need to be submitted?
A national workplace benefits report found that 56% of workers had access to a plan covering mental-health providers to some degree, while the median annual maximum was $750 in 2021, down from $1,001 in 2020. The report is available through the Mental Health Commission of Canada's workplace benefits research. These figures describe broad workplace patterns, not your specific plan, so your own booklet and insurer confirmation take priority.
Copy-and-paste question for your insurer: “Can you confirm whether counselling with this provider designation is eligible, my annual maximum and remaining balance, any per-session or reasonable-and-customary limit, whether a referral is required, and whether dependents are covered under this benefit?”
Check dependent eligibility separately
A family plan doesn't always mean every family member has identical access. A 2026 BC public-sector benefits guide describes counselling coverage up to $1,000 per year for a covered individual, while some BC government benefits notices state that mental-health benefits may not extend to eligible dependents under particular plans. Review the wording for spouses, children, co-parents, and other dependents before booking on someone else's behalf.
It won't replace confirmation from your insurer, but organised records can make follow-up easier.
Choosing a Therapist Your Plan Will Reimburse
The right therapist needs to meet two conditions: the relationship must feel suitable for your needs, and the plan must recognise the provider's credentials. Neither consideration should automatically override the other. A clinician who looks ideal on paper may not be eligible under your plan, while an approved provider may not have the experience or approach you're looking for.
Start by asking the therapist or clinic for their exact professional designation and registration information. Then give that information to your insurer. Don't rely only on a website description such as “therapist” or “counsellor,” because insurers often process claims according to formal designations.
Compare your billing options
| Feature | Direct Billing | Pay and Submit Receipt |
|---|---|---|
| How it works | The clinic submits the claim to the insurer after the appointment. | You pay the clinic, receive an itemised receipt, and submit the claim yourself. |
| Cash flow | You may pay only the portion not covered, if the insurer approves the claim. | You pay the full appointment amount first and wait for reimbursement. |
| Control | The clinic handles much of the submission process. | You can review the receipt and submit it through your preferred insurer channel. |
| Potential limitation | Not every insurer or provider supports direct billing. | You must ensure the receipt includes the information your insurer requires. |
| Best question to ask | “Which insurer and provider designation can you direct bill?” | “What information will appear on the receipt?” |
A therapist outside your insurer's approved list may still be the best clinical fit. Ask whether the provider can supply documentation for you to submit, and confirm with the insurer whether an exception, reassessment, or alternate designation is possible. Don't book several sessions assuming approval will be granted later.
Match clinical fit with practical access
Consider the issues you want help with, the clinician's training, and whether their way of working feels respectful and understandable. Ask whether they support individual, couples, family, child, or youth counselling if that distinction matters to you. For a spouse, child, or co-parent, confirm both the therapist's suitability and the dependent's eligibility under the plan.
Availability affects continuity too. A provider with daytime, evening, or weekend appointments may be easier to attend consistently. In-person sessions can suit clients who value a dedicated space, while phone or secure virtual counselling may help people manage travel, mobility, privacy, work, or family responsibilities. Check whether your insurer treats virtual care the same way as in-person care before relying on that option.
Understanding Direct Billing and Receipts for Counselling
Direct billing can feel simpler because the clinic submits the claim after your appointment. The insurer then assesses the service, and you pay any amount that isn't covered. This can reduce paperwork, but it doesn't guarantee approval. The provider designation, plan category, annual maximum, and reimbursement limit still determine what the insurer pays.
Receipt reimbursement follows a different route. You pay for the session, request an itemised receipt, and submit it through the insurer's portal, app, email process, or paper form. This approach gives you direct control over the claim, but you need to monitor deadlines, documentation, and the remaining benefit balance.
Know what should appear on the receipt
Before leaving an appointment, check that the receipt identifies:
- Client name: The person who received counselling
- Service date: The date the appointment occurred
- Provider identity: The clinician's name and professional designation
- Registration details: The provider or registration number, if required
- Service description: Counselling, psychological services, or the appropriate benefit category
- Amount paid: The amount charged and whether it was paid
- Clinic information: Contact details and any insurer-required billing information
If a claim is partially paid, read the insurer's explanation rather than assuming the therapist made an error. The insurer may have applied a reasonable-and-customary limit, a co-insurance rule, a remaining annual maximum, or a provider eligibility restriction. Ask the clinic for clarification only after you know which rule affected the claim.
Coordinate benefits carefully
If you have coverage through your employer and another plan, such as a spouse's plan, tell both insurers about the second policy. Submit according to each insurer's coordination-of-benefits instructions. Keep the original receipt and the first insurer's explanation of benefits, because the second insurer may require evidence of what was already reimbursed.
A useful question before your first session is: “If direct billing isn't available, can you provide an itemised receipt with your registration number and the exact designation my insurer requires?” That single conversation can prevent repeated requests for missing information.
Understand the trade-off
Direct billing is helpful when upfront payment would create stress, but you may have less control over the timing and details of the submission. Paying and submitting gives you a clear paper trail, though you need enough available funds to pay first and wait for reimbursement.
Neither pathway changes the clinical service. Choose the process that matches your insurer's rules, your cash flow, and your comfort with paperwork.
How to Submit Claims and Avoid Common Reimbursement Delays
A claim usually moves smoothly when the service, provider, date, and benefit category all match the insurer's records. Delays often arise from small discrepancies, such as a missing registration number or a receipt submitted under “medical services” instead of “counselling.” Save every document until the insurer confirms the claim is complete.
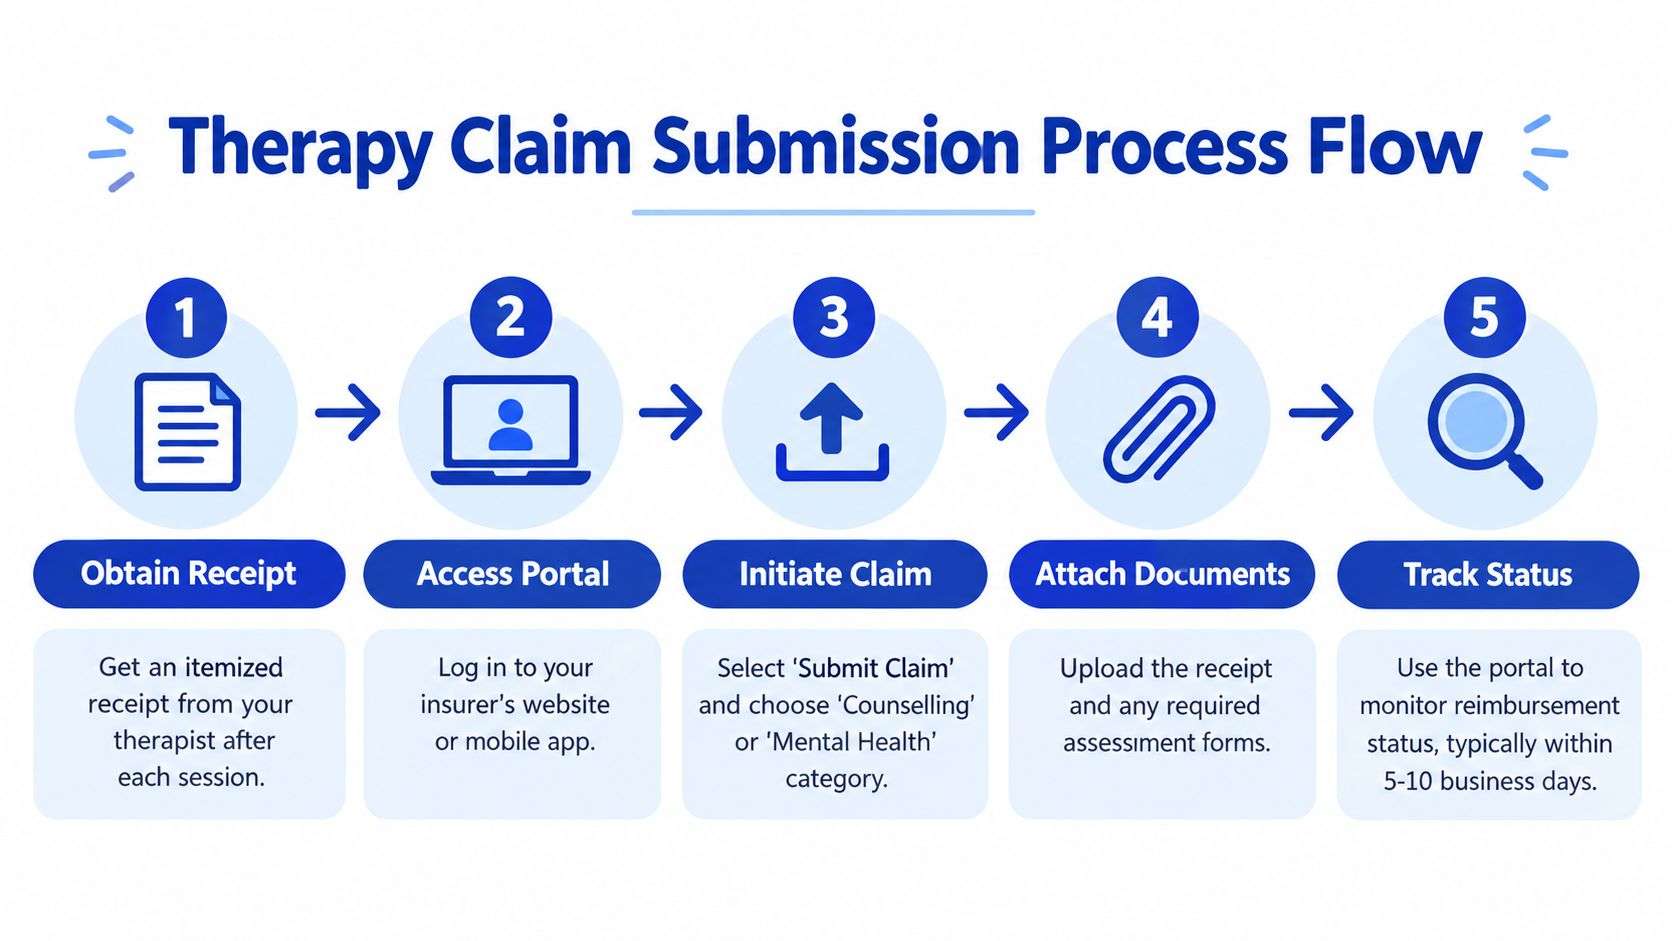
Follow the claim path
- Obtain the receipt: Request an itemised receipt after each session, whether you use direct billing or submit the claim yourself.
- Open the insurer portal: Log into the website or mobile app connected to your extended health plan.
- Choose the benefit category: Select “Counselling,” “Psychological Services,” or “Mental Health,” depending on your insurer's wording.
- Attach documents: Upload the receipt and any referral, assessment, or coordination-of-benefits form requested.
- Track the result: Record the claim number and check the portal for approval, partial reimbursement, or a request for more information.
The precise processing timeline varies by insurer, so don't treat an estimated portal message as a guarantee. If the insurer asks for additional documents, respond promptly and keep copies of what you send.
Watch the annual maximum
A common mistake is scheduling frequent sessions without checking how quickly the annual maximum will be used. The Canadian Psychological Association's 2023 employer coverage update reports a median annual maximum of $750 for mental-health counselling, and 61% of employers capped coverage between $0 and $1,000. The same update reports an average annual maximum of $2,006, which highlights how widely plans differ.
If your plan reimburses only part of each appointment, the balance may still count toward the plan's eligible limit, depending on the policy. Ask how claims are calculated before you schedule a regular appointment pattern. A steady plan developed with your counsellor may help you avoid exhausting coverage unexpectedly, but treatment frequency should be based on clinical need and safety, not insurance alone.
Special rules after a motor vehicle accident
ICBC accident benefits include counselling as a covered medical expense. The standard initial limit is 12 counselling sessions within the first 12 weeks after a motor vehicle accident, and ICBC may cover additional treatment when a doctor or ICBC medical adviser recommends it.
Tell the counsellor and insurer if your therapy relates to an accident. ICBC-funded care may follow a different approval and billing process than extended health benefits, so submitting the same session to multiple payers without guidance can create confusion.
If a claim is denied or underpaid
Use this short review:
- Check the designation: Does the receipt show the provider category your plan accepts?
- Check the date: Does the service date match the appointment?
- Check the category: Was the claim entered under counselling or mental-health services?
- Check the limit: Has the annual maximum or per-session allowance been reached?
- Check the dependent: Is the person who attended eligible under the plan?
- Call for a written reason: Ask the insurer what document or rule caused the decision.
A denial isn't a judgement about whether you need therapy. It usually reflects an administrative or contractual rule that can sometimes be clarified or corrected.
Making Your Benefits Last and Finding Supportive Next Steps
Benefits work best when they support a broader care plan rather than determine every clinical decision. Ask your counsellor how often sessions might be useful, what signs would suggest adjusting that frequency, and how you can continue practising skills between appointments. You can also review your balance regularly instead of waiting until a claim stops processing.
If your maximum is limited, discuss pacing openly. Your counsellor may help you identify the most urgent goals, create between-session practices, and plan a review point. If you reach the limit before your concerns have eased, ask the insurer whether the next benefit year, another eligible provider category, an EAP, or a separate coverage pathway applies. Don't stop support abruptly if doing so could place your wellbeing at risk.
Some people also use educational resources to reflect on patterns, sleep, stress, or emotional responses between appointments. It isn't a substitute for assessment or counselling, especially when symptoms are severe or safety is a concern.
Questions clients often ask
Can my spouse or child use my counselling benefit?
Not necessarily. Dependent eligibility varies by plan, and some benefits apply only to the covered employee or individual. Ask the insurer whether the specific spouse, child, or other dependent is eligible before an appointment is booked.
What happens if the wait for counselling is longer than my benefit period?
Contact the insurer and ask how the plan defines the benefit year, claim date, and eligibility period. If the wait affects your wellbeing, ask your primary care provider or local health service about other appropriate supports while you wait. Benefits should help with access, but they don't replace urgent care when someone is at immediate risk.
Can I plan sessions around a new benefit year?
You can ask your counsellor and insurer how unused limits, renewal dates, and claim processing work. A new benefit year may reset an allowance, but the exact rule belongs to your plan. Confirm the date in writing so you can make decisions based on your actual coverage.
What if my preferred counsellor isn't eligible?
Ask the counsellor for their designation and registration details, then speak with the insurer about the reason for ineligibility. You may need to choose another eligible provider, request a review, or use a different coverage route. Clinical fit matters, but a claim can only be reimbursed when the plan's conditions are met.
You don't have to solve every benefits question before reaching out for support. A counsellor or clinic can explain its billing process, while your insurer can confirm what the plan will reimburse. Interactive Counselling offers in-person, phone, and secure virtual counselling for individuals, couples, families, children, and youth, with daytime, evening, and weekend availability in a safe, inclusive environment. Learn more by visiting Interactive Counselling and bring your benefits questions into the conversation.
Clinically Reviewed By
Amy Mosset, MCP, RCC-S
Amy Mosset is a Master Practitioner in Clinical Counselling, Clinical Supervisor, and the owner of Interactive Counselling. She provides trauma-informed, evidence-based care and clinical supervision to registered therapists, with a focus on ethical practice, client safety, and high-quality therapeutic outcomes.