You've decided it's time to speak with a counsellor in Vernon. You may even have found a therapist whose approach feels right. Then you open your benefits booklet and run into unfamiliar terms: eligible practitioner, paramedical maximum, reimbursement rate, benefit year. It's understandable if the paperwork feels almost as stressful as the problem that brought you to counselling. For more information, see our Vernon couples counselling.
Extended health benefits can make therapy more accessible, but they don't all work the same way. The provider's professional credential, your plan's annual limit, the claim category, and the type of counselling you choose can all affect what you receive back. A few questions before booking can prevent an unpleasant surprise later. For more information, see our counselling in Vernon.
Why Extended Health Benefits Matter for Therapy in Vernon
A Vernon resident might begin looking for counselling after months of anxiety, a difficult separation, grief, trauma, relationship strain, or persistent low mood. They may have provincial health coverage and reasonably assume that counselling will be paid in the same way as a visit to a physician. In British Columbia, that assumption often leads to confusion because MSP doesn't generally cover private community-based counselling and psychotherapy. For more information, see our couples counselling.
As a result, extended health benefits are often the practical route people use to help pay for therapy. The Province of British Columbia's employee counselling guidance says eligible employees may claim up to $1,000 per person per calendar year when services are delivered by a recognized social worker, registered clinical counsellor, or registered psychologist, with the practitioner registered in B.C. for reimbursement claims. Those rules illustrate why both the provider's credentials and the plan wording matter. British Columbia's counselling support guidance provides the provincial example.
The usual process also places some responsibility on the client. You generally pay the therapist first, receive a receipt, and submit that receipt to your insurer. That means your plan's maximum, reimbursement rate, deductible, and remaining balance can directly affect whether counselling feels financially manageable.
A reassuring starting point: checking coverage isn't a test you have to pass before asking for help. It's simply a way to understand the financial side of care.
National evidence helps explain why this preparation matters. A Mental Health Commission of Canada report found that about 60% of Canadians had some form of private employment-based insurance, while typical annual therapy limits were only $500 to $1,000. Those limits may help with an initial set of appointments, but they often don't fund ongoing therapy by themselves. You can also review this plain-language overview of mental health insurance costs for broader context about how coverage can vary.
The key point is simple: extended benefits are real support, but they're rarely unlimited. Confirming the details before you book lets you decide how to use the available coverage thoughtfully, without delaying care because the paperwork feels unfamiliar.
Understanding What Your Plan Actually Covers
A plan can say that counselling is covered while still excluding the particular professional you want to see. In B.C., the credentials most commonly relevant to reimbursement are a Registered Clinical Counsellor, a registered psychologist, and a recognized social worker. Some plans may also use other eligible categories, but you need to confirm the exact wording instead of relying on a general statement such as “mental health services included.”
The title matters because insurers process claims according to the practitioner category listed in your contract. A therapist may be highly qualified, yet a claim can still be declined if their credential isn't included or if their registration doesn't meet the plan's requirements.
The two limits people often confuse
Plans commonly restrict counselling in one or both of these ways:
- Per-session limit: The insurer reimburses only up to a specified amount for each appointment, even if the therapist's fee is higher.
- Annual maximum: The plan reimburses eligible counselling until you reach a total dollar cap for the calendar or benefit year.
A plan may also reimburse a percentage of each eligible expense rather than the full amount. For example, the contract might combine a per-visit reimbursement rule with a total annual pool. You'll need to ask how those rules work together, not just whether counselling appears in the benefits summary.
The access gap is significant. Statistics Canada reported that 58.8% of people who met diagnostic criteria for a mood, anxiety, or substance use disorder said they needed counselling or psychotherapy during the prior 12 months, but only 43.8% received some counselling or psychotherapy. That is a 15.0 percentage-point gap, and the Mental Health Commission of Canada notes that no province or territory provides universal insurance coverage for counselling, psychotherapy, and psychological services. These findings appear in the commission's report on access to counselling and psychological services.
Workplace coverage also varies considerably. The same report found that the median annual maximum for mental health counselling in Canadian workplaces was $750 in 2021, down from $1,001 in 2020, and that 72% of plans capped coverage at $1,000 or less. Those limits can cover an important beginning, but they may not support sustained care without planning.
For comparison, a University of British Columbia benefits guide describes a specific Sun Life plan that covers 100% of fees for licensed psychologists, social workers, or registered clinical counsellors, up to $3,000 per person per benefit year. That's an example of one plan, not a standard that applies to every Vernon resident. It also shows why broad advice about therapy coverage, including information about in-person therapy Manhattan NYC, can't replace reading your own Canadian benefits contract.
How to Verify Your Benefits Before Booking
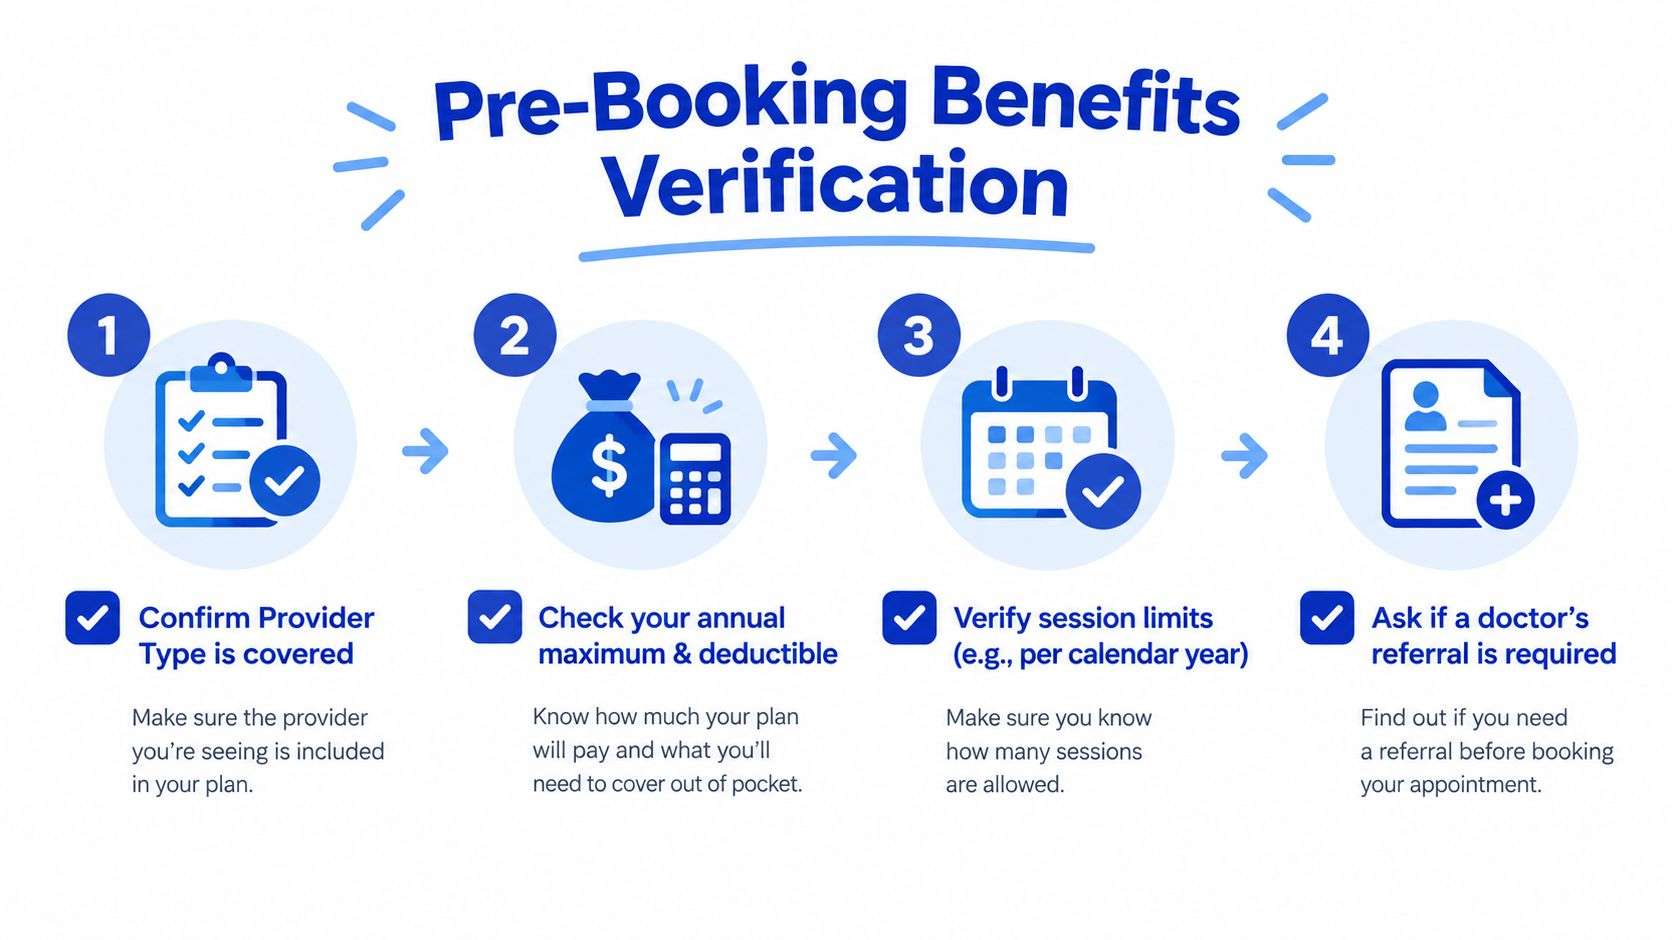
The most useful benefits check happens before your first appointment, while you still have time to clarify anything unclear. Keep your benefits booklet, insurer app or member portal, and the therapist's professional designation nearby.
Start with the provider credential
Ask your insurer whether the plan covers the exact professional you're considering:
- Registered Clinical Counsellor: Confirm that the plan recognizes RCC services and whether B.C. registration is required.
- Registered psychologist: Ask whether the benefit applies to a psychologist specifically, and whether any separate psychological-services category exists.
- Recognized social worker: Check whether the plan requires a registered social worker and whether the claim must include a registration number.
Don't stop at “Does my plan cover therapy?” Ask, “Is counselling with this exact professional designation eligible under my plan?”
Confirm the financial rules
Find out the annual maximum, the reimbursement rate, and whether a deductible applies. Then ask whether the limit is shared with other services or reserved specifically for counselling.
You should also check whether the plan uses a calendar year or a separate benefit year. If you've already submitted claims for counselling or other services in the same pool, ask for your current remaining balance. The amount shown in your member portal may be more useful than the original maximum printed in your booklet.
Ask about referrals and session rules
Many extended health plans allow people to self-refer and book directly with a counsellor, without a physician's referral. Independent B.C. guidance explains that plans may reimburse either a percentage per session, a fixed annual maximum, or both, so confirm the rule that applies to your policy through this counselling benefits guide.
Ask these questions in one call or secure message:
- Is this practitioner's credential covered?
- What is the annual maximum, and how much remains?
- Is there a per-session reimbursement limit?
- Is a physician referral or pre-authorization required?
- Are phone and secure virtual sessions eligible?
- What receipt information must the therapist provide?
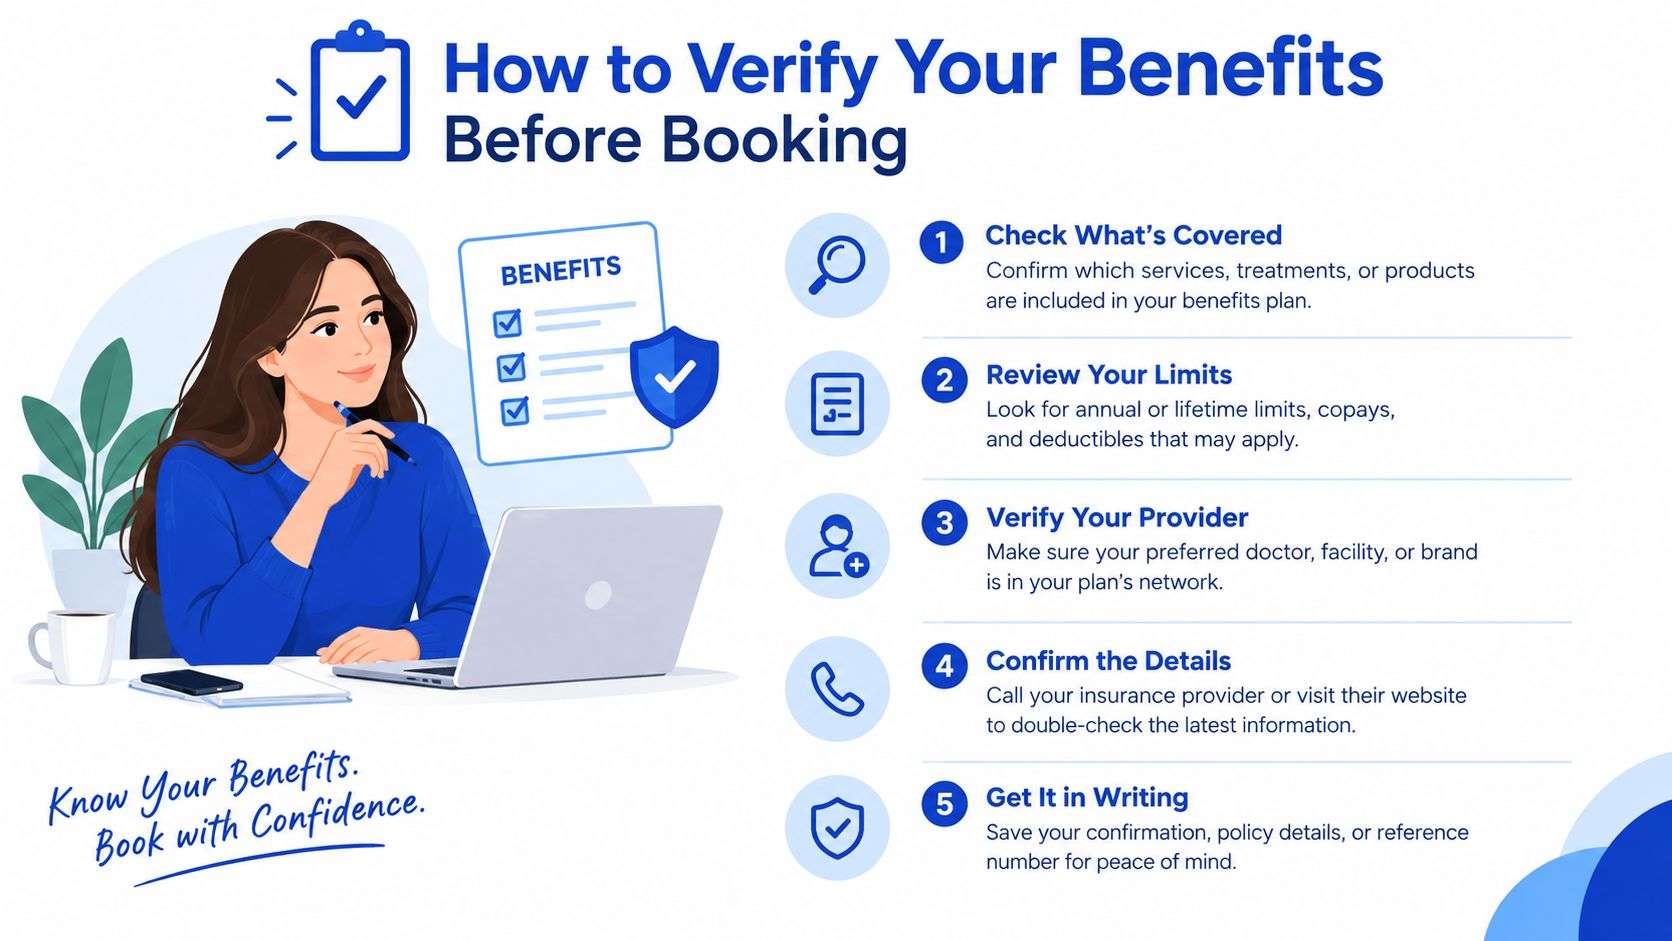
Write down the representative's name, the date of your enquiry, and any reference number. If the answer is unclear, request written confirmation. Benefits staff handle these questions regularly, and asking them early is a practical form of self-advocacy.
Choosing the Right Counselling Format for Your Life
Coverage is only one part of making counselling workable. The format needs to fit your actual week, not an imaginary schedule with unlimited time, privacy, and energy.
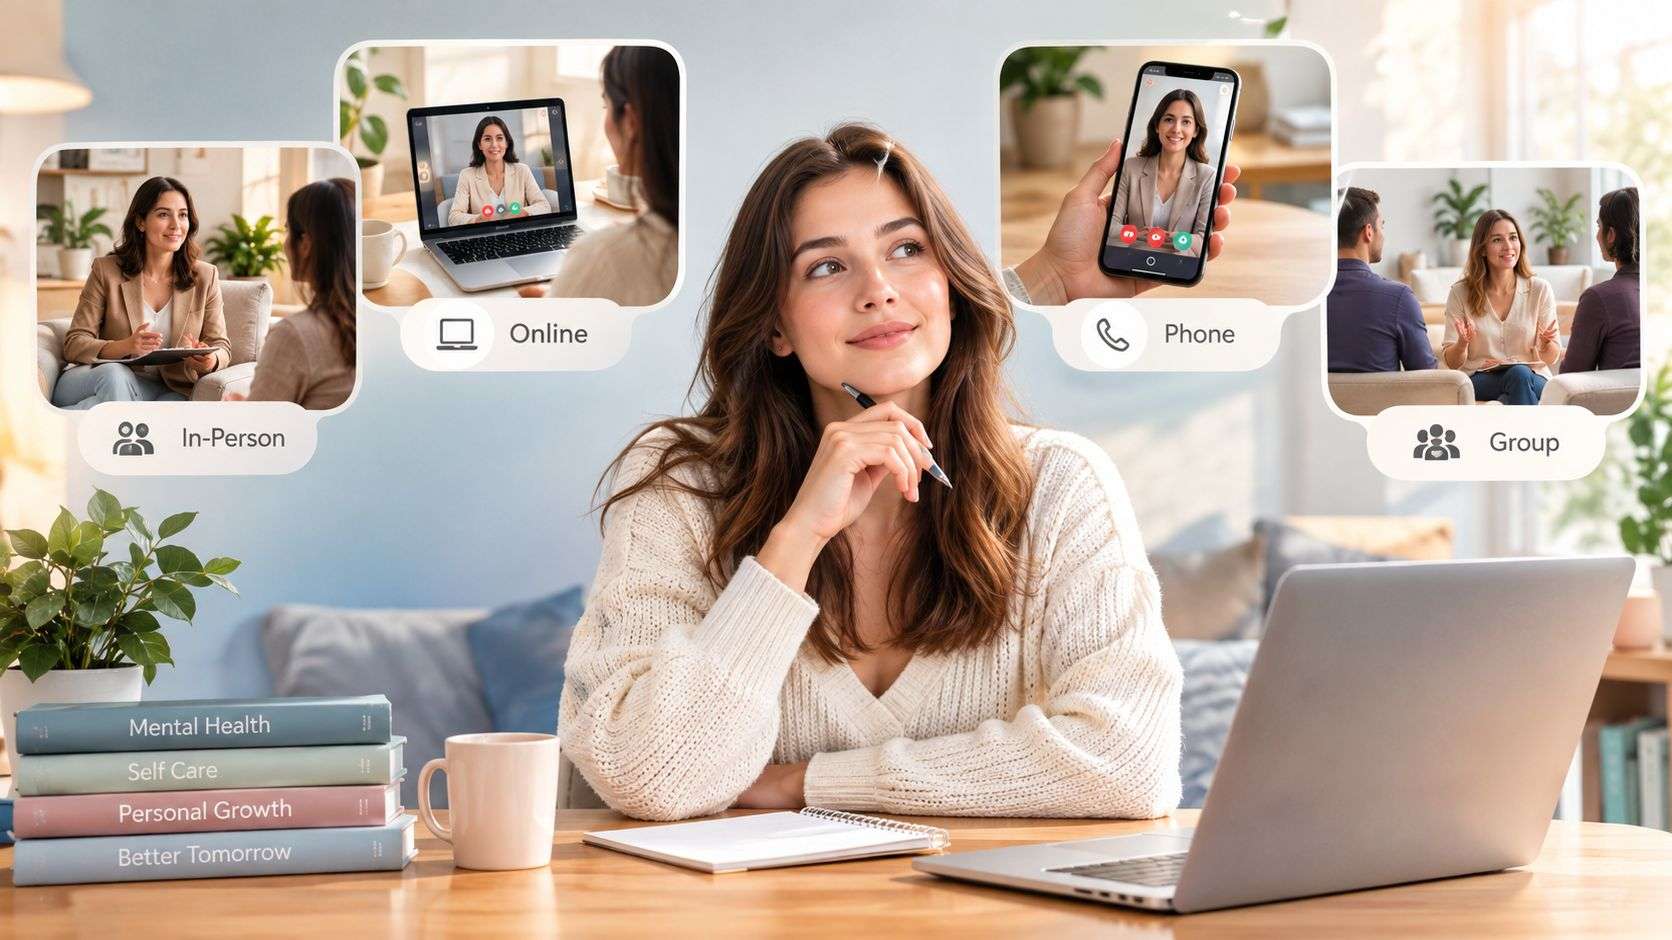
In-person counselling may suit you if you value a dedicated setting away from home or find face-to-face communication more comfortable. Consider travel time, transportation, weather, and whether attending an appointment in Vernon fits around work, caregiving, or school.
Phone counselling can be useful when internet access is unreliable or when you feel more at ease speaking without being on camera. You'll still need a private place where you won't be overheard. It's worth confirming that your insurer treats phone sessions as eligible counselling before scheduling.
Secure virtual counselling can reduce travel and make it easier to attend from home, work, or another private location. Before choosing it, check your internet connection, headphones, background noise, and whether anyone else could enter the room unexpectedly. Privacy affects the quality of the conversation as much as convenience does.
Most extended health plans may accept these formats when the provider is eligible, but that isn't universal. Ask the insurer directly, and ask the counselling office what information appears on receipts for each format.
Interactive Counselling offers in-person, phone, and secure virtual sessions, with daytime, evening, and weekend availability. That range can help clients choose a format around real responsibilities, while still leaving the insurance question for the individual plan to confirm.
A useful decision rule is to choose the format you're most likely to attend consistently. A theoretically convenient appointment won't help if the setting leaves you distracted, uncomfortable, or unable to speak freely.
Submitting Claims and Getting Reimbursed
For many Vernon clients, the first claim feels more complicated than it is. The standard process is usually: pay for the appointment, receive a complete receipt, and submit it through the insurer's member portal.
A typical online claim
- Sign in to your member portal. Use the insurer's website or mobile app, and select the claims area.
- Choose the claim category. Counselling often appears under “Paramedical” or “Health,” depending on the insurer.
- Enter the service details. Provide the practitioner's name, date of service, amount paid, and professional registration number.
- Upload the receipt. Make sure the image or document is legible and includes the required information.
- Review before sending. Check the provider category, date, amount, and registration details against the receipt.
- Submit and retain the confirmation. Save the claim number or confirmation screen in case the insurer asks for clarification.
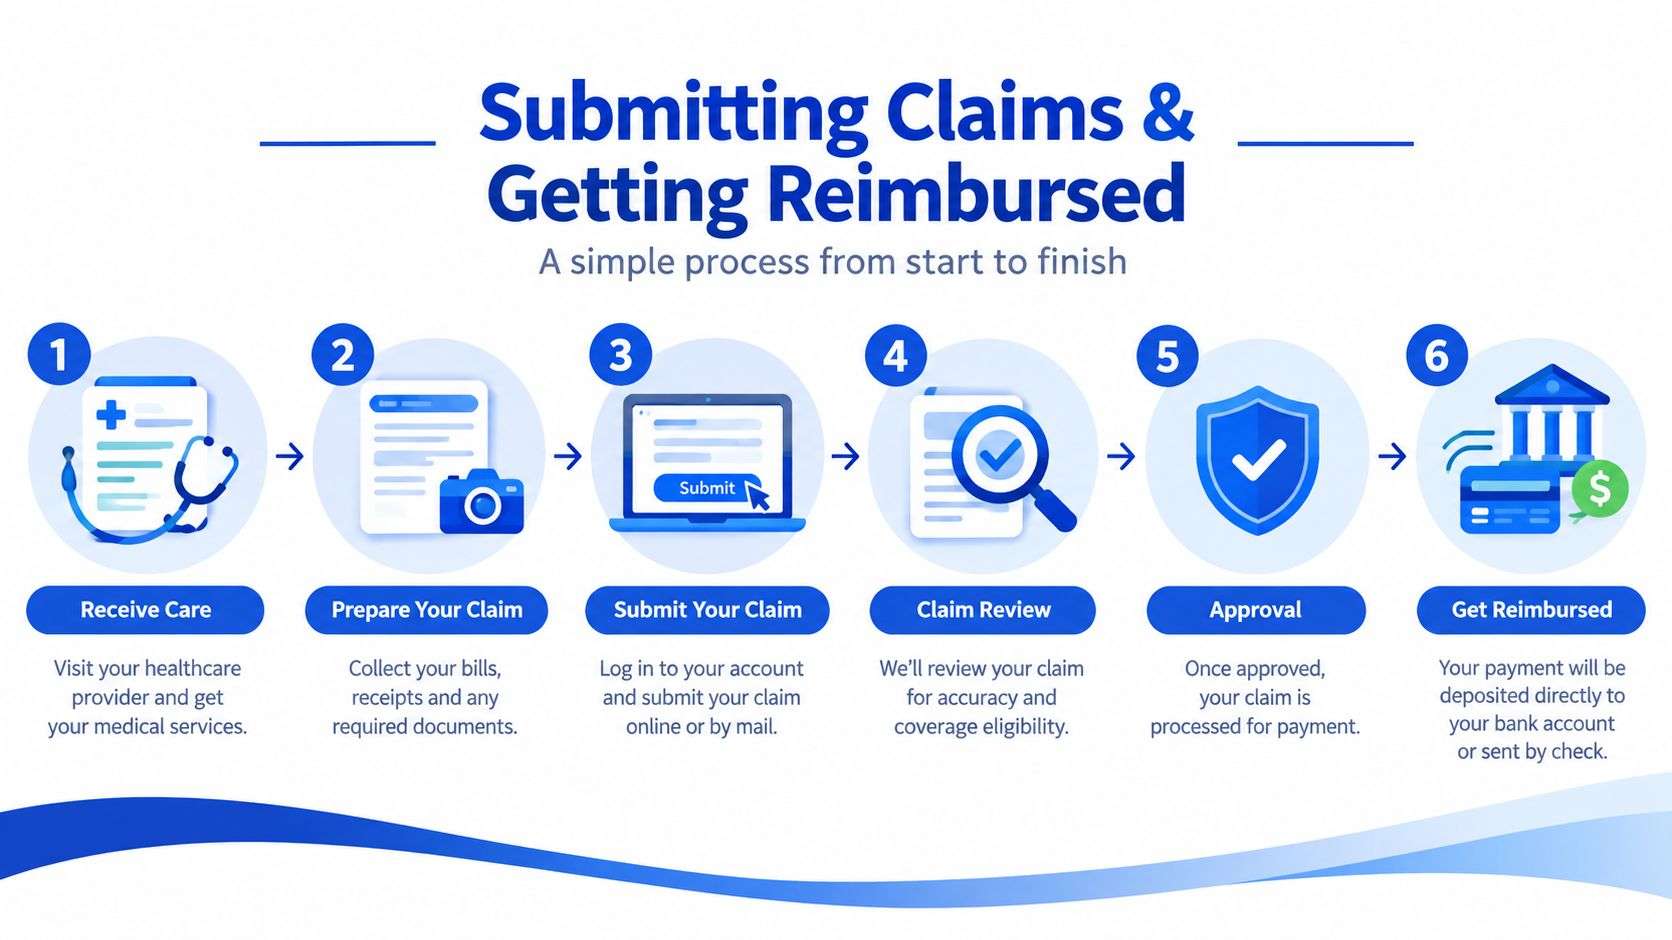
The Province of British Columbia explains that claims are subject to plan maximums and reimbursement rates, and that reimbursement may depend on services from a recognized social worker, registered clinical counsellor, or registered psychologist registered in B.C. In other words, a receipt alone doesn't guarantee payment. The insurer also checks whether the service and practitioner meet the contract rules.
Small errors can create large delays
Common problems include selecting the wrong claim type, leaving out the practitioner's registration number, and uploading a blurry receipt. If a claim is declined, read the explanation carefully before assuming the service isn't covered. The issue may be a missing field, an incorrect category, or a request for additional documentation.
Online claims are often processed within 1 to 5 business days when direct deposit is enabled, according to the practical workflow described in major Canadian benefit portals and the provincial guidance. Keep copies of receipts and approval messages until the claim has been fully processed and the reimbursement appears in your account.
Before submitting: Compare every field in the portal with the receipt. A quick review can prevent an avoidable follow-up.
Common Coverage Surprises and How to Handle Them
“Counselling is covered” doesn't always mean every counselling situation is reimbursable. Couples counselling, for example, may be treated differently from individual therapy, particularly if the plan requires the named patient to receive a recognized clinical service. Ask whether relationship or family counselling is eligible and whose name must appear on the claim.
Provider restrictions can also appear late in the process. One plan may recognize a Registered Clinical Counsellor, registered psychologist, and social worker, while another may use a narrower list. B.C. public-sector benefit changes show that plan wording remains uneven, with one 2026 plan offering a combined $1,000 annual maximum while other plans still referenced $750 per year. These are plan-specific examples, not universal rules, as shown in the Province of B.C.’s information about services covered by MSP.
Questions that deserve a direct answer
- Does the limit reset by calendar year or benefit year? The answer affects when unused coverage expires and when a new allowance becomes available.
- Is pre-authorization required? Some plans may require approval before the first session or before services from a particular provider category.
- Does the plan use a narrow credential list? Ask for the exact professional titles accepted by the insurer.
- Are couples, family, child, and youth sessions treated differently? The patient and service description may affect adjudication.
If a claim is declined, request a written explanation and ask how to submit a review. Provide the receipt, the practitioner's registration information, and any referral or pre-authorization documentation requested by the insurer. If the decision still seems inconsistent with your plan wording, contact your benefits administrator or human resources department and keep a record of each response.
Benefit plans are changing in some areas, including expanded eligible provider categories, but those changes remain plan-specific. Don't assume that a newer benefit rule applies to your employer or family policy without checking the current wording.
Frequently Asked Questions About Counselling Benefits
Does ICBC-funded counselling interact with private benefits?
ICBC-funded counselling for a motor vehicle accident is handled through the applicable claim process, not automatically through your personal extended health pool. Ask the counsellor or ICBC how billing will be coordinated before submitting the same service to another insurer.
What if my annual limit isn't enough?
Use your remaining coverage deliberately and ask the therapist about planning care around your benefits. You can also contact 8-1-1 or 2-1-1 in B.C. to ask about available community supports, as described by HelpStartsHere BC.
Can a parent's plan cover counselling for a child or youth?
It may, but eligibility depends on the plan's dependent rules, the child's age, the provider credential, and the service category. Ask the insurer whose information must appear on the receipt before booking.
Do I need a doctor's referral?
Many plans allow self-referral, but your own policy may require a referral or pre-authorization. Confirm this directly with the insurer.
Counselling can begin with one manageable question: which provider credentials does my plan recognize, and what amount remains? Interactive Counselling supports individuals, couples, families, children aged five and older, and youth through in-person, phone, and secure virtual counselling in Vernon.
Interactive Counselling offers evidence-informed support for anxiety, depression, grief, trauma, PTSD, relationships, parenting, family concerns, and life transitions. Visit Interactive Counselling to learn more about available counselling formats and how to request a receipt for your extended health claim.
Clinically Reviewed By
Amy Mosset, MCP, RCC-S
Amy Mosset is a Master Practitioner in Clinical Counselling, Clinical Supervisor, and the owner of Interactive Counselling. She provides trauma-informed, evidence-based care and clinical supervision to registered therapists, with a focus on ethical practice, client safety, and high-quality therapeutic outcomes.