You've found a counsellor in Penticton who seems like a good fit. You're ready to reach out, but then a practical worry appears: Will my extended health plan cover these sessions? The answer may depend on details that aren't obvious from the word “counselling” in your benefits booklet. For more information, see our Penticton grief counselling.
You might be looking for support with anxiety, depression, grief, trauma, relationship stress, or a difficult transition. You may also be trying to understand whether your plan covers a Registered Clinical Counsellor, how much it will reimburse per visit, and whether your remaining annual maximum will be enough for consistent care. These questions can feel overwhelming when you're already carrying a lot. For more information, see our counselling in Penticton.
Extended health benefits work best when you understand them before your first appointment. A quick review can prevent a denied claim, clarify what you'll pay yourself, and help you decide whether to use an Employee Assistance Program, ICBC coverage, public resources, or your regular benefits. This guide explains the process in plain language, with a focus on the three checks that matter most for extended health counselling in Penticton. For more information, see our grief counselling.
Introduction to Extended Health Counselling in Penticton
A Penticton resident might begin by searching for counselling after months of restless sleep and anxious thoughts. Another person may be coping with grief, trauma, or tension at home. They find a practitioner whose experience feels appropriate, then pause before booking because their benefits booklet uses unfamiliar terms such as “paramedical services,” “psychological services,” or “registered provider.”
That pause is understandable. Coverage isn't determined only by whether someone calls themselves a counsellor. Insurers often specify which professional designations qualify, how much they'll reimburse for each appointment, and the total amount available during a benefit period. If one of those details doesn't match your plan, you could receive less reimbursement than expected or have a claim declined.
Private counselling and psychotherapy in British Columbia aren't covered by MSP, so many clients use extended health benefits or pay out of pocket. The B.C. government's counselling support guidance explains that eligible employees may claim counselling from recognized providers such as a registered social worker, registered clinical counsellor, or registered psychologist, depending on their plan. It also notes that clients generally pay first and submit the receipt for reimbursement.
A helpful starting point: Treat your benefits plan as a set of rules to verify, not as a promise that every counselling service will be reimbursed.
The limits can be modest. A 2023 summary from the Canadian Psychological Association reported a median annual counselling maximum of $750, unchanged from 2021 and down 25% from $1,001 in 2020. The same summary found that 61% of employers offered between $0 and $1,000 in annual counselling coverage. For longer-term concerns, a modest cap can be used quickly.
That doesn't mean you shouldn't seek help. It means a little planning matters. By checking your provider eligibility, per-visit reimbursement, and annual maximum before booking, you can make informed decisions about session frequency and other available supports.
What Extended Health Counselling Covers in British Columbia
A Penticton client may have counselling coverage through an employer, union, school, municipality, or individual extended health plan, while another person at the same café may have completely different rules. These benefits sit outside MSP, and the policy contract decides what qualifies, how much the insurer pays, and when the available amount resets.
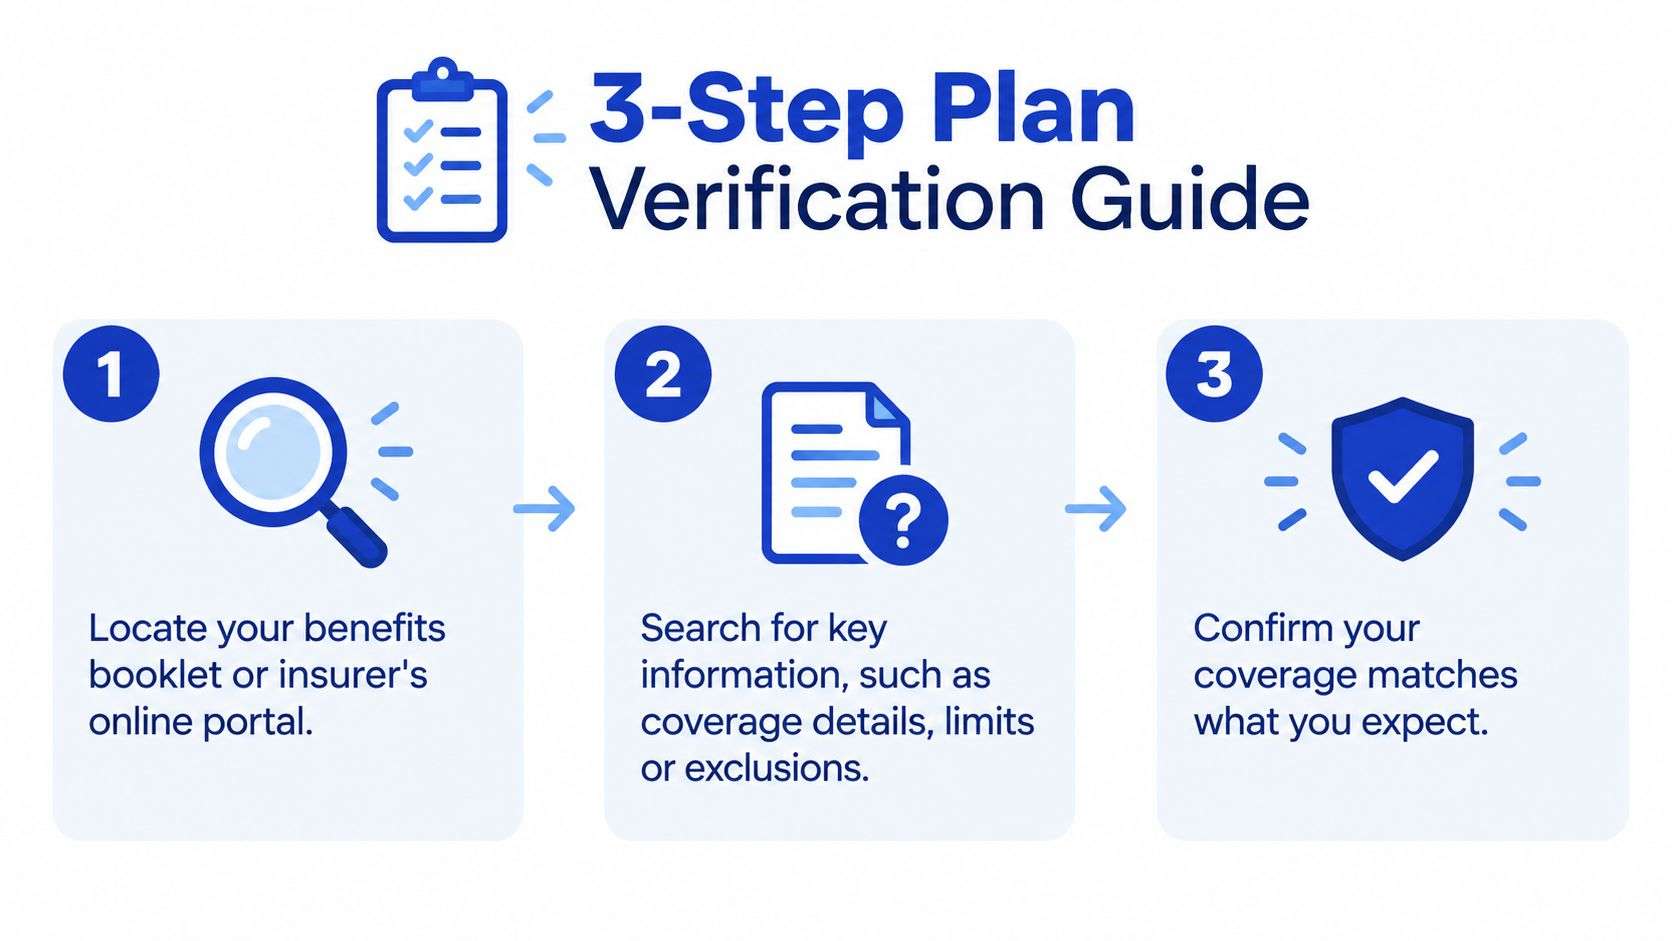
The first check is the provider designation. A plan may recognize Registered Clinical Counsellors, registered psychologists, and registered social workers, or it may place those professionals in separate categories. “Counsellor” and “therapist” are not always insurance categories. Ask the practitioner for their exact registration wording, then compare it with the benefits booklet or insurer's eligibility list.
The second check is the per-visit reimbursement. Your plan might pay a percentage of an eligible session, a fixed dollar amount, or the full eligible fee up to a limit. A session can be clinically appropriate and still leave you with a balance if the appointment fee exceeds the reimbursed amount.
The third check is the annual maximum. This is the total counselling amount available during the benefit year or calendar year. It works like a small pool of funds. Each reimbursed appointment draws from that pool, so the per-visit rate and annual maximum need to be read together.
For illustration, a plan might offer an annual mental-health maximum somewhere between $500 and $3,000, with reimbursement set between 50% and 100% of an eligible session. These are examples of possible plan designs, not a promise about your policy. Review the exact wording before assuming a session is covered. This British Columbia extended health benefits overview provides further context on how plan limits can be structured.
Coverage categories can also change. A 2026 audit reported that municipal coverage for registered clinical counsellors rose from 12 to 22 municipalities since 2023, an 83% increase, according to Benefits and Pensions Monitor. Broader recognition does not remove the need to verify your own policy.
Understanding what is mental health parity explains why mental-health benefits are discussed alongside other health coverage. Parity is a policy principle. Your benefits booklet remains the practical guide to provider eligibility, reimbursement, and the annual maximum.
How to Check Your Plan Before You Book
The safest time to verify coverage is before scheduling your first appointment. You can usually find the information in your insurer's online portal, your benefits booklet, or by calling the provider-services number on your benefits card.
Write down the answers rather than relying on memory. Insurance language can be dense, and having a short record makes it easier to compare providers or review a claim later.
Check one, provider designation
Search your plan for terms such as “counselling,” “clinical counselling,” “psychological services,” “social work,” or “paramedical practitioners.” Look specifically for Registered Clinical Counsellor or RCC if you're considering that provider type.
Don't assume that “licensed counsellor” or “therapist” automatically matches the insurer's approved category. Ask the provider for their exact designation and registration details, then give that wording to the insurer.
Questions to ask include:
- Is a Registered Clinical Counsellor eligible under my plan?
- Are registered psychologists and social workers covered under the same category?
- Does the provider need to be registered in British Columbia?
- Is a physician referral or diagnosis required?
- Are virtual and telephone counselling sessions eligible under the same rules?
Check two, the per-visit rate
Your plan may reimburse the entire eligible amount, a percentage of the session, or a set amount per appointment. A plan with a generous annual maximum can still leave you paying more than expected if the per-visit reimbursement is limited.
Ask the insurer to explain the calculation using your expected session fee. You don't need to disclose personal clinical details. The useful information is the provider designation, the appointment format, and the plan limits.
For example, if the insurer says it reimburses only part of each eligible appointment, ask whether the remaining amount counts toward the annual maximum. Also ask whether longer appointments are billed differently. A clear answer helps you and your counsellor discuss a schedule that fits both your needs and your coverage.
Check three, the annual maximum and reset date
Find the total counselling maximum and the date on which it renews. Some plans reset by calendar year, while others use a benefit year connected to your employer or plan anniversary.
Check whether counselling shares a cap with psychological testing or other services. UBC provides one concrete example of a plan offering 100% coverage up to $3,000 per person per benefit year for licensed psychologists, social workers, or Registered Clinical Counsellors, with counselling and psychological testing counting toward the same limit, as described in UBC's benefits guidance. Your plan may be structured differently.
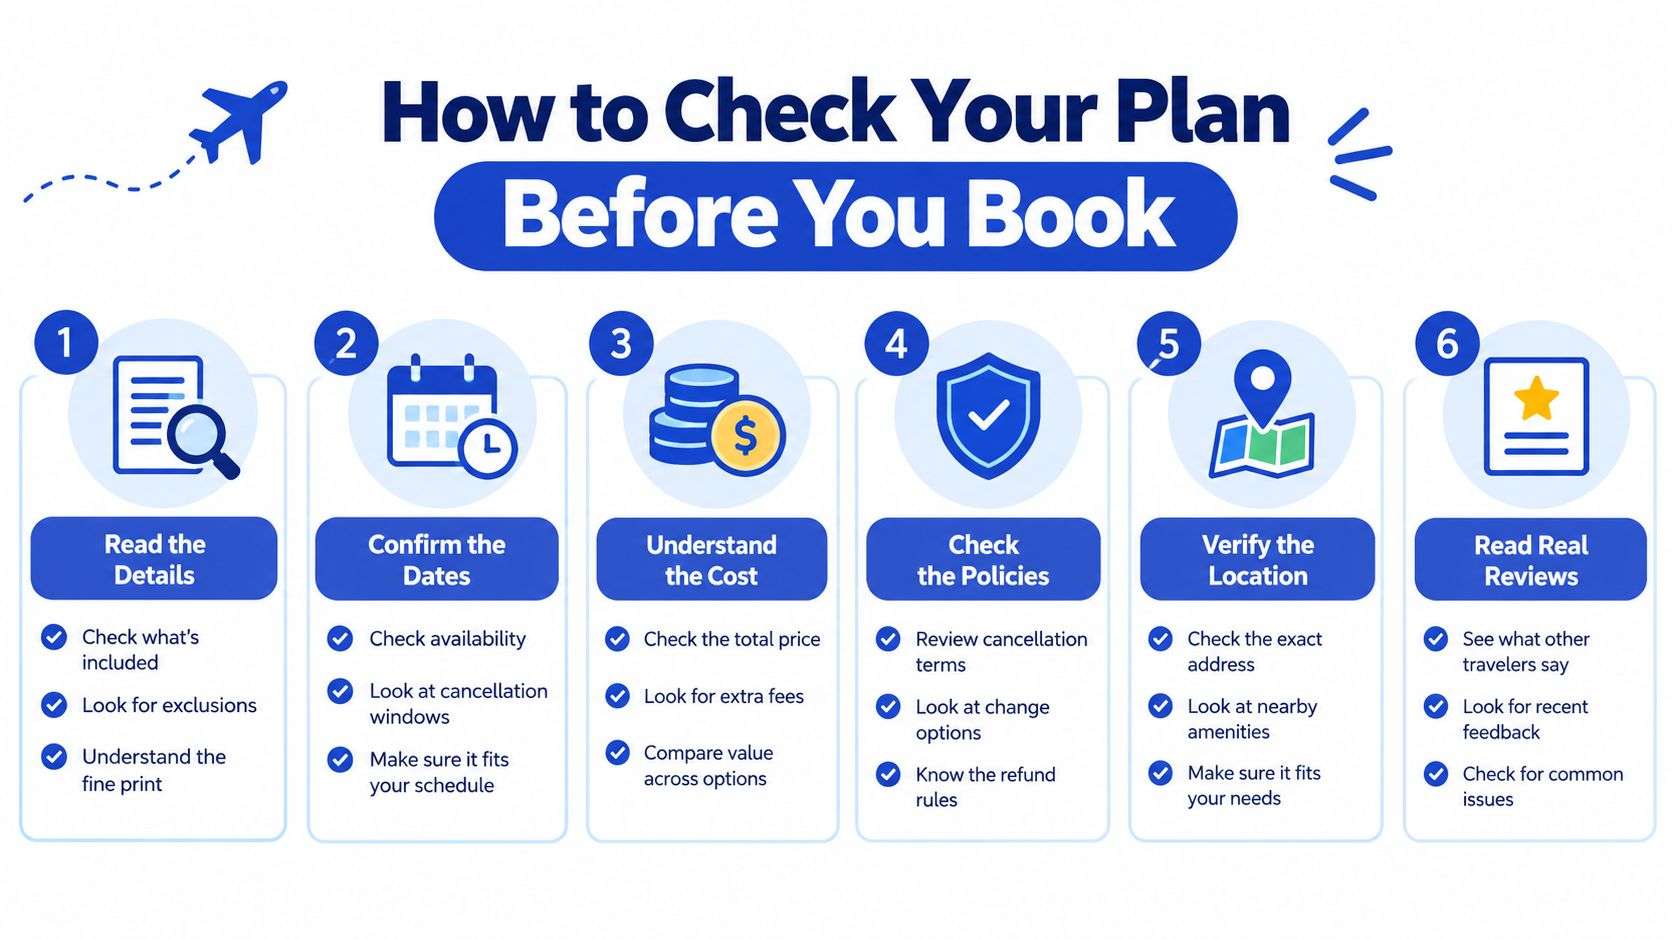
Before you book, confirm these points:
- The provider's designation is eligible.
- The provider is registered where the plan requires.
- The reimbursement percentage or fixed amount is clear.
- The annual maximum is clear.
- The reset date is recorded.
- Testing and counselling do or don't share a maximum, depending on the policy.
Practical rule: Ask the insurer to confirm coverage in writing through the portal or email whenever possible. Keep that confirmation with your receipts.
A short phone call can prevent a stressful surprise. If the insurer gives you a reference number, save it with your notes.
How Claiming Works and How to Combine Benefits Wisely
Once eligibility is confirmed, the next question is how payment will move between you, the counsellor, and the benefit provider. Some practices offer direct billing to certain insurers. In that arrangement, the provider submits the claim and you pay any amount the insurer doesn't cover.
With reimbursement, you pay the session fee, receive a detailed receipt, and submit it through your insurer's portal, app, or paper process. The B.C. government's counselling support page describes this pay-first, submit-for-reimbursement model for eligible counselling support.
A proper receipt usually includes the client's name, appointment date, service description, amount paid, provider name, designation, registration information, and payment confirmation. Your insurer may request additional details, so ask what it needs before submitting a claim.
Choosing Your Claiming Pathway
| Pathway | How It Works | Best When |
|---|---|---|
| Employee Assistance Program | An employer-arranged program provides a defined amount of confidential counselling support. | You need an accessible starting point or short-term support and your workplace offers an EAP. |
| ICBC Enhanced Care | Eligible crash-related counselling is funded through ICBC under its program rules. | Your need for counselling follows a motor-vehicle accident. |
| Extended health benefits | You use an eligible provider, pay directly or use direct billing, and claim within your plan limits. | You need ongoing care or your concern isn't connected to a motor-vehicle accident. |
| Health spending account | Eligible expenses may be submitted under the account's rules after regular benefits are applied. | Your extended health plan leaves a balance and your HSA permits counselling expenses. |
| Public or community support | You access publicly funded or community-based mental-health services according to their eligibility rules. | Your plan is limited, unavailable, or not the right resource for your current needs. |
Sequence matters because some supports are time-limited. ICBC's Enhanced Care program, launched in May 2021, automatically pre-approves up to 12 counselling sessions after a motor-vehicle crash. The sessions are available during the first 12 weeks after the accident, and no physician or nurse-practitioner referral is required before starting care, according to this ICBC counselling guide.
If ICBC applies, confirm that pathway before using your regular extended health benefits. If an EAP offers short-term sessions, ask whether you can use those first and then transition to extended health for continuing care. Don't submit the same appointment to multiple payers. Double-claiming can create repayment problems and may complicate future claims.
A counsellor can help you discuss the practical sequence without deciding for you which benefit provider must pay. The insurer, employer, EAP administrator, or ICBC representative can confirm the rules for your situation.
Making Your Annual Coverage Last and Avoiding Common Pitfalls
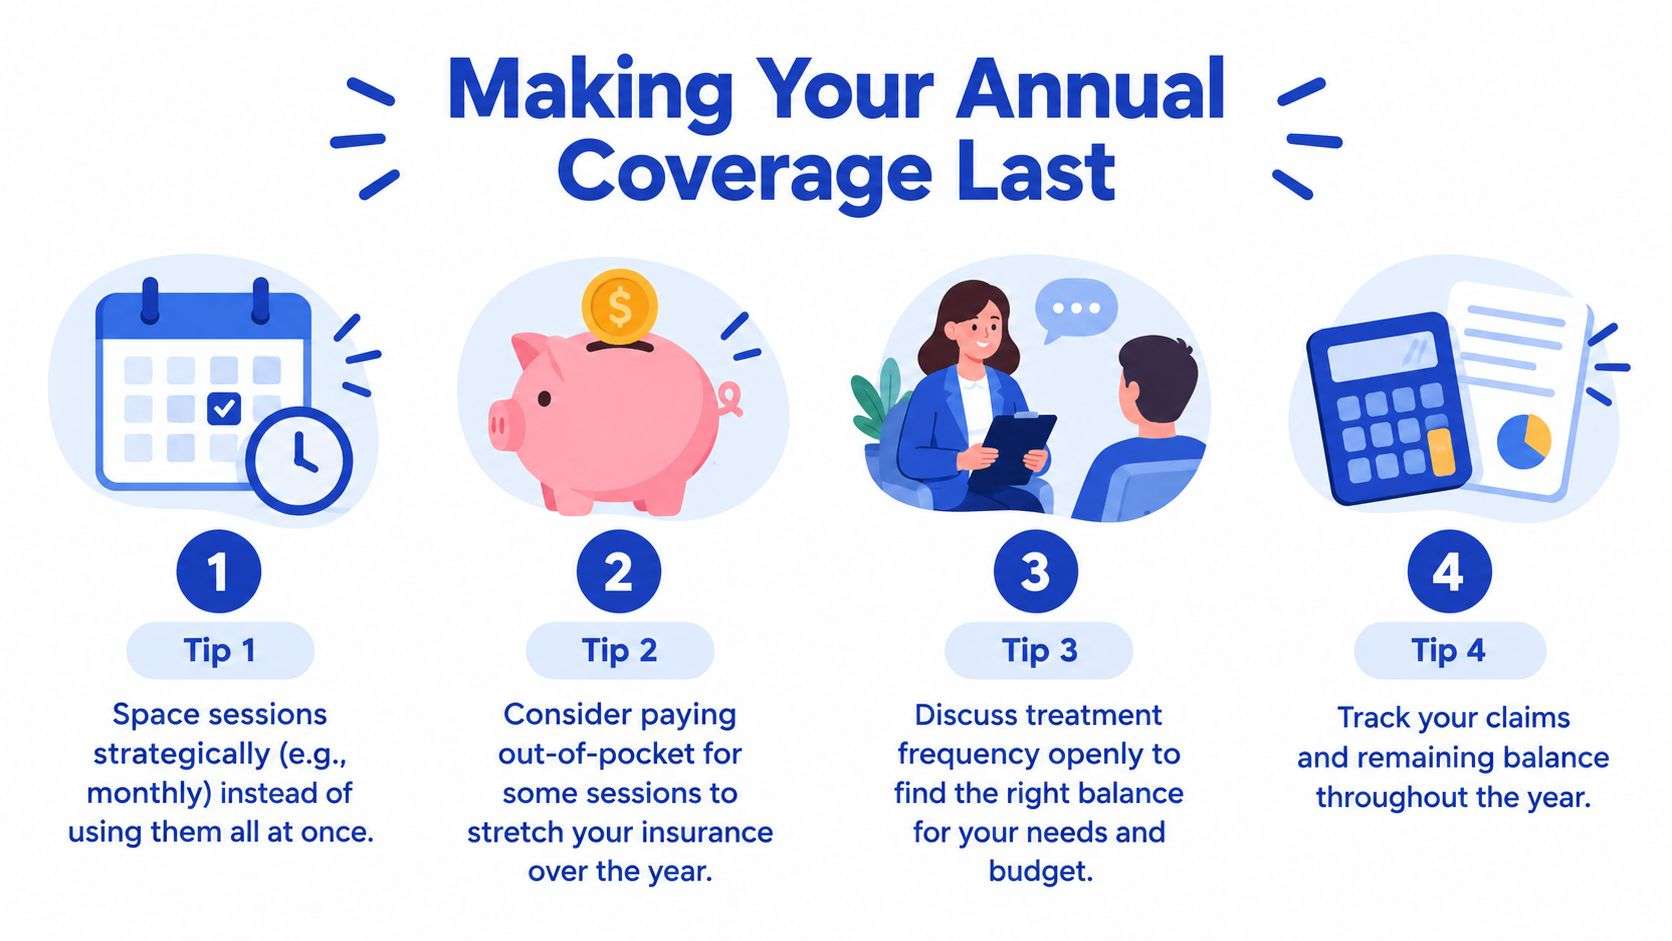
A capped benefit is a limited resource, so the question isn't only how to claim it. The better question is how to use it in a way that supports meaningful care throughout the period when you need it.
Canada's benefits market reported that claims for paramedical services such as mental health and massage rose 16% in 2024, while $143.3 billion was paid in total health benefits, according to the Canadian Life and Health Insurance Association. Growing use can place pressure on plans that have relatively small counselling maximums.
A provincial BC study estimated that 250,855 people were diagnosed with major depressive disorder, and that the health system spent more than $1.5 billion over two years on newly diagnosed cases. The study reported that more than a quarter of those costs occurred during the first 12 weeks after diagnosis, as described in the Mental Health Commission of Canada research report. This supports early help, but early help still needs to be financially realistic.
Build a plan with your counsellor
Some people benefit from frequent appointments at the beginning, while others may prefer a less frequent rhythm. The right schedule depends on clinical need, safety, goals, and availability, not insurance alone.
Talk openly about your annual limit and reimbursement rules. You might agree on a focused treatment plan, review progress at regular points, and adjust session frequency when appropriate. Paying for some appointments yourself may help preserve coverage for periods when support is especially valuable, but that decision should reflect your circumstances rather than a rule that applies to everyone.
Keep a simple record of:
- Claims submitted: Note each appointment and submission date.
- Reimbursement received: Compare the insurer's payment with the expected amount.
- Remaining maximum: Update the balance after every processed claim.
- Reset date: Record when your available coverage renews.
Common mistakes include assuming every counsellor qualifies equally, overlooking a percentage co-payment, missing a calendar-year reset, and forgetting that psychological testing may share the same maximum. Keep receipts even after reimbursement. They may be useful for your records, a health spending account, or tax-related documentation, depending on the relevant rules.
Financial care is part of therapeutic care: A sustainable schedule is often more helpful than using every available session quickly and then stopping because the cap has been reached.
BC is also expanding low- or no-cost mental-health services for adults, which shows that public supports remain important alongside private benefits. If extended health isn't enough for the care you need, ask about public, community, virtual, or targeted options rather than delaying support until symptoms become harder to manage.
Frequently Asked Questions and Gentle Next Steps
What if my plan doesn't list Registered Clinical Counsellors?
Call the insurer and ask which provider designations qualify under the counselling or psychological-services benefit. Give the representative the practitioner's exact designation and registration information. If an RCC isn't eligible, ask whether a registered psychologist or social worker is covered, and request the answer in writing.
Can I change providers during the benefit year?
Usually, your plan's annual maximum applies to eligible services rather than to one specific practitioner, but the provider must still meet the plan's requirements. Check whether changing designations affects reimbursement and whether a new assessment or referral is required.
Are virtual sessions reimbursed?
Many insurers now address video and telephone appointments in their policy wording, but reimbursement depends on your plan and the provider's eligibility. Ask specifically about secure virtual counselling, telephone sessions, the provider's location, and receipt requirements before booking.
What if my benefits run out?
Discuss options with your counsellor before the maximum is exhausted. You may consider a different session rhythm, an eligible health spending account, an EAP, ICBC where relevant, or public and community supports. If you're in immediate danger or experiencing a mental-health crisis, contact emergency services or a local crisis resource rather than waiting for an insurance decision.
Seeking counselling is a considered step toward support, not a sign that you've failed to manage on your own. Review your three coverage checks, keep your records organised, and choose a care plan that respects both your needs and your resources.
Interactive Counselling offers evidence-informed counselling for individuals, couples, families, children aged 5 and older, and youth, with support for concerns including anxiety, depression, grief, trauma, PTSD, relationships, parenting, and life transitions. To learn how in-person, phone, or secure virtual sessions may fit with your extended health plan, visit Interactive Counselling at your own pace.
Clinically Reviewed By
Amy Mosset, MCP, RCC-S
Amy Mosset is a Master Practitioner in Clinical Counselling, Clinical Supervisor, and the owner of Interactive Counselling. She provides trauma-informed, evidence-based care and clinical supervision to registered therapists, with a focus on ethical practice, client safety, and high-quality therapeutic outcomes.